International Travel · Domestic Travel
Is credit card travel insurance reliable?
March 13, 2026
Many people are unsure whether to buy travel insurance or rely only on the insurance offered by their credit card. And, most of the time, the question doesn't even come up: the traveler simply goes with the benefit offered by the bank. That's understandable — after all, why pay for another policy if, in theory, the card already "guarantees" that protection?
The problem is that, in practice, card insurance usually works very differently from what most people imagine, and that gap between expectation and reality usually only shows when something unexpected or an emergency happens. Worse: in an unfamiliar place, with costs in dollars or euros and urgent decisions to make. So, before depending exclusively on this option, it's worth understanding a few points that make all the difference to your safety (financial, physical and emotional) and to your peace of mind on the trip.
You need to understand how card insurance usually works in practice. Based on our experience and on feedback frequently found on consumer complaint sites such as Brazil's Reclame Aqui, we've gathered the main points to watch out for so you can avoid unpleasant surprises.
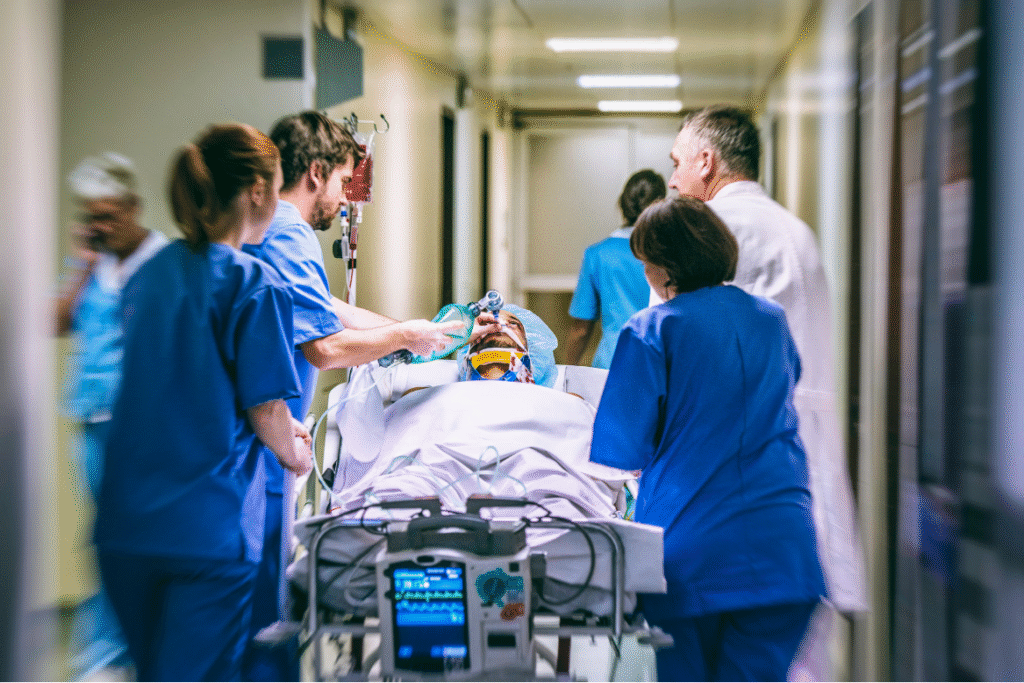
Unexpected problems are unpleasant, especially on a trip. But which insurance really protects you when they happen?
Reimbursement system
In most cases, card insurance works through reimbursement. This means that, in an emergency, travelers have to pay the costs out of their own pocket and only then request reimbursement from the insurer. That detail alone completely changes the equation, for two main reasons.
The first is the most immediate and simple: you may not have the funds available when you need care. On international trips, the cost of consultations, tests and procedures tends to be high, and not everyone has the financial margin to cover it right away. Even in "minor" situations, an unexpected event can eat up a significant part of the travel budget, affecting tours, shopping, restaurants and even basic expenses planned for the trip.
The second scenario is when the traveler does have the money, but the financial impact is significant. An unexpected expense can upset your finances for months and, in more sensitive situations, may even lead to loans or installment plans that were not in the plans.
Limited support
Another important aspect is the type of service. Credit card insurance often relies on self-service channels, such as toll-free call centers and online forms, which in urgent situations can end up hindering more than helping. It's common to find accounts of travelers who spend hours waiting in line, especially at peak times, weekends and holidays.
And even when contact finally happens, the process tends to be laborious or even unworkable, since the documentation, records, requests and case follow-up fall entirely on the traveler. Some details make this scenario even more exhausting at critical moments:
- In many cases, only the cardholder can open and handle the claim, which becomes a problem if they are incapacitated, hospitalized or without access to a phone.
- Even if the service is in your language, the local reality is not: hospital documents, instructions, clinic names, information and contacts may be in another language, which increases the risk of misunderstandings.
- The lack of active follow-up also weighs heavily. Instead of someone handling your case from start to finish, you may need to call several times, repeat information and start over if the call drops.
Denied reimbursement
There is a risk few people consider: what if the insurer simply denies the reimbursement? Believe it or not, this happens more often than you think and, many times, you only find out after the emergency, when you have already paid out of your own pocket.
Some recurring reasons:
- Overlooked clauses and conditions (the "fine print") can exclude coverage depending on the type of incident, the circumstances of the claim or even specific medications and hospital services used in treatment.
- Procedures not followed correctly: without clear instructions on what to do, many people follow their instincts in an emergency and only later discover the insurance required documents, steps or proof that were not provided.
- Outsourced commitment: since the service is usually outsourced to a company linked to the card benefit, just to round out the bank's perks package, the success of the execution is outsourced too. In some cases, when you seek help from the bank, you'll hear answers like "unfortunately I have no control over your issue".
Limited, inflexible coverage
Card-linked insurance usually has predefined coverage, limits and little room for customization, which can leave gaps in precisely the situations that are common on international trips. The coverage may not include parts of your itinerary or your travel profile. For example:
- Certain scenarios may be excluded (for example, sports, adventure tours, hiking, or trips with pregnant travelers and children, depending on the rules).
- High-value items (electronics, photo equipment or work tools) are usually not covered.
- Important expenses such as lost luggage, ticket rebooking costs, accidental death and even repatriation may be outside the scope, or have limits that don't match the real risk.
- Restrictive clauses may rule out coverage depending on the origin and context of the claim.
In other words, "free" coverage may give a sense of security, but when something happens it can leave you unprotected or stuck with an uncertain reimbursement process.
So what should you choose?
Here, our recommendation is to do a self-assessment. Before relying only on card insurance, answer honestly:
- In the worst-case scenarios, how much might I need to spend on an emergency abroad?
- Would I have that amount available right away, without compromising my finances?
- Does my itinerary include activities that often have restrictions, such as hiking, sports or adventure tours?
- Am I carrying expensive or essential items (including for work)?
- How much stress and bureaucracy am I willing to face in the middle of the trip if something happens?
- What do I gain and what do I lose by relying only on this option?
- Would I be comfortable paying for an emergency abroad out of my own pocket and only later risk discovering I won't be reimbursed?
- Am I willing to spend time after the trip requesting reimbursement, following the insurer's bureaucratic processes?
These questions are not meant to "scare" you. They are meant to align expectations with reality. If you want to travel with more peace of mind, without depending on uncertain reimbursement and a bureaucratic process at critical moments, personalized travel insurance tends to be the safer choice, because it is designed for the traveler and for the kind of trip you are taking.
And there is a practical point many people value: with the agency's guidance and mediation, you don't have to face the whole process of filing a claim, gathering documents and following up on your own. That way, you can enjoy the destination more lightly and, if something happens during the trip, you have support to handle the situation more safely.
If you need travel insurance suited to your destination, your profile and your travel style, talk to the BrazTrip team and request a no-obligation quote. We'll help you choose the right coverage so your experience is as light as it should be.
Your next journey starts here